Scoda Tubes Q4FY26 Power Idea: 47% Upside on Capacity Expansion & Margin Tailwinds
India’s stainless steel pipes and tubes industry is entering a multi-year upcycle. Scoda Tubes stands out as a structural growth story with expanding capacities, strong approvals, and rising profitability.
| Company | Target Price (₹) | Upside | Key Theme |
|---|---|---|---|
| Scoda Tubes Ltd | 240 | 47% | Capacity Expansion & Margin Upside |
What we like in the company
- Scoda tubes is the leading seamless stainless steel (SS) pipes & tubes manufacturer in India which has grown its land parcel and its capacity by 8-10x in the last 5years.
- Scoda has build its past track record with approvals across large Oil & gas, general engg., power and EPC companies in India and abroad.
- The backward integration hot piercing plant setup in FY23 is the major reason for the high teen margins and qualification in large government tenders.
- An all-round management team which is working on reducing cost, increasing marketing reach, adding new approvals and adding capacities.
Near-term triggers
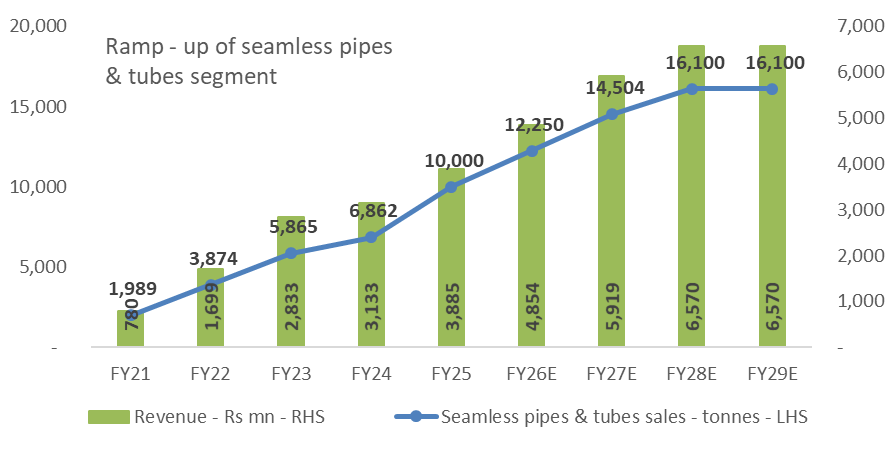
- New seamless SS capacity commissioned in Oct’25, along with strong demand from power and new approvals from ADNOC, SABIC and Reliance + rise in exports to the US should all lead to strong volume growth over FY25-FY28E.
- Addition of new welded pipes capacity which will be sold to existing customer base along with new customers in the process industries should add to the volume growth.
- Margins are expected to improve due to optimum utilization of the hot piercing plant and improvement in product mix.
Earnings Outlook
- Termination in sales of low margin hollow tubes sales in FY28, lower working capital cycle for welded pipes and optimum utilization of the hot piercing plant, is together expected to improve return ratios and ramp up cash conversion for Scoda tubes.
- We are factoring in 22%/20%/40% CAGR in Revenue/EBITDA/PAT over FY25-28E due to the robust volume growth and operating leverage.
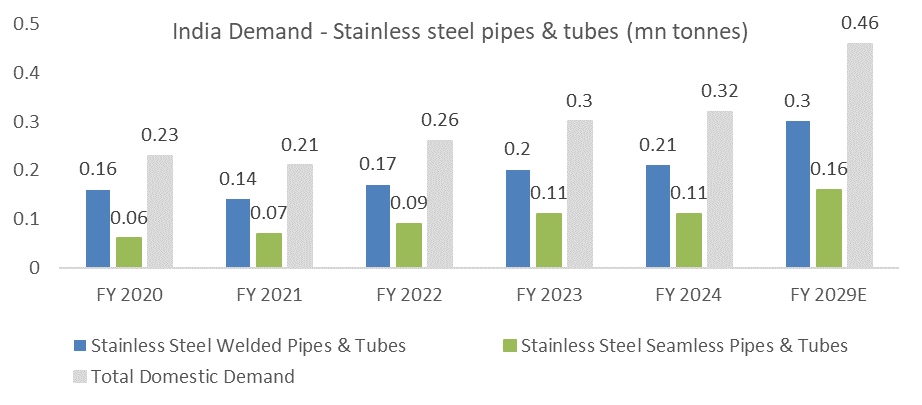
- The industry is driven by tailwinds of strongly growing demand for SS pipes along with a deficit supply scenario benefiting Scoda tubes.
Strong demand tailwinds + supply deficit industry
Valuation and view
- We ascribe 19x multiple to Sept ‘27E EPS and arrive at a target price of Rs 240 and a BUY rating. At CMP of Rs163, Scoda trades at a very attractive 15.4x/ 11.2x FY27/ FY28E PE Ratio.
- Key Risks: Weakness in stainless steel prices, import duties and reducing quotas on exports.
Optimal revenue potential of the seamless SS pipes capacity
Key financials (Rs mn)
| Particulars | FY24 | FY25 | FY26E | FY27E | FY28E |
|---|---|---|---|---|---|
| Revenues (Rs mn) | 3,999 | 4,849 | 5,849 | 7,261 | 8,709 |
| EBITDA | 588 | 781 | 884 | 1,110 | 1,358 |
| EBITDA Margin (%) | 14.7 | 16.1 | 15.1 | 15.3 | 15.6 |
| Adjusted PAT | 183 | 317 | 504 | 634 | 876 |
| Adjusted EPS (Rs) | 142.6 | 7.2 | 8.4 | 10.6 | 14.6 |
| P/E (x) | NM | NM | 19.4 | 15.4 | 11.2 |
| EV / EBITDA (x) | NM | NM | 11.1 | 8.9 | 6.9 |
| ROE (%) | 28.8 | 21.1 | 12.0 | 13.3 | 15.9 |
| ROCE (%) | 11.2 | 12.6 | 9.4 | 10.6 | 13.8 |
FAQs on Scoda Tubes Ltd Power Idea
Q1. Why is Scoda Tubes a Q4FY26 Power Idea?
Strong capacity expansion, backward integration, and rising demand from power, oil & gas and exports position Scoda for multi-year growth.
Q2. What is driving margin improvement?
Optimal utilization of the hot piercing plant, better product mix, and exit from low-margin hollow tube sales.
Q3. What is the growth outlook?
Revenue/EBITDA/PAT CAGR of 22%/20%/40% over FY25–28E driven by volume growth and operating leverage.
Q4. What are the key risks?
Volatility in stainless steel prices, import duty changes, and export quota restrictions.
Before You Trade, Strengthen Your Foundations with These Guides
- For a stronger understanding of indicators such as RSI, VWAP, and trendlines, check our 👉 Technical Analysis Fundamentals section.
- Want to refine your risk-reward planning? Explore our insights on 👉 Position Sizing & Risk Management Strategies.
Disclaimer: - Investments in securities market are subject to market risk, read all the related document carefully before investing. https://www.mnclgroup.com/research-disclaimer
Related Knowledge Cafe
TDPS Power Idea Q4FY26: Structural Demand, 25% Upside Potential
Scoda Tubes Q4FY26 Power Idea: 47% Upside on Capacity Expansion & Margin Tailwinds
Rashi Peripherals Q4FY26 Power Idea: 40% Upside on Memory Price Tailwinds
CRISIL Q4FY26 Power Idea: Rating Cycle Upswing & Valuation Comfort