Redington Ltd - Where technology meets scale | Initiating Coverage Report
We initiate coverage on Redington Ltd with a BUY rating and target price of Rs 370. Redington stands as a dominant and well-diversified technology distributor in India, spanning mobile devices, cloud and software solutions, and ICT products. The company enjoys strong partnerships with global majors such as Apple (largest distributor in India), HP, Dell, Lenovo, Samsung and many other brands. Redington is at an inflection point in its high-growth, scalable cloud and software business, and it aims to expand 3x over the medium term. Rising premiumization trends, a forthcoming PC refresh cycle, and the upcoming Windows upgrade are expected to further accelerate demand across its Mobility and Electronics (MSG & ESG) segments., mirroring the growth seen in broader electronics manufacturing and distribution ecosystems. Valuations at 9.7x FY27E EPS offer an attractive entry point - BUY.
Cloud and Software Solution - Game changer:
Redington’s Software Solutions Group (SSG) and Cloud segment are set to be key value drivers, with revenues expected to grow 3x over the next 4-5 years, expanding their contribution from 15% to over 30%+. Anchored by strong partnerships, this subscription-led, high-retention business (95%+) delivers 5.5-6% gross margins versus 4–5% in hardware. Its proprietary CloudQuarks platform supports provisioning, billing, analytics, and lifecycle management for 40,000+ resellers and SMBs, fostering deep engagement. With cloud adoption in India, MEA, and ASEAN still nascent compared to the West where software forms ~25% of IT distribution Redington has a long runway for sustainable growth and margin expansion, Similar to niche technology solution providers expanding their digital footprints.
Premiumization & Refresh Cycles - Twin growth levers:
Redington is well-positioned to benefit from rising premiumization in mobility and an upcoming PC refresh cycle slated to start from H2FY26. Premium smartphones from Apple, Samsung, Motorola, and Google are driving higher ASPs, supported by Redington’s strong premium retail network. On the enterprise side, deferred upgrades and the Windows 10 end-of-support in Oct '25 are set to trigger a major replacement wave, led by AI-enabled PCs. This aligns with the momentum seen in India's evolving AI infrastructure landscape, where hardware capabilities are rapidly scaling to meet computational demands. These trends strengthen Redington’s growth visibility across consumer and enterprise segments, while its expansion into 300+ cities deepens reach beyond metros.
Best-in-class distributor on all parameters:
Redington is the 8th-largest distributor globally and the clear leader in India, the UAE, and Saudi Arabia. Its 40,000+ channel partners across Tier 1–4 cities provide unmatched reach, while exclusive partnerships ensure strong vendor stickiness. The company delivers steady cash flows through disciplined working capital management and maintains a healthy 0.3x debt-to-equity ratio (best in the industry). Beyond distribution, Redington is evolving into a solutions-driven enterprise with investments in its cloud marketplace, AI integration, and sustainability verticals such as solar and device refurbishment.
Valuations, view & risks:
We are factoring in 14.0%/18.6%/22.1% Revenue/EBITDA/Adj. PAT CAGR over FY25-28E. We value the company at an average of 14x PE & 2x PB on Sept’27E to arrive at TP of Rs370. BUY. Our positive stance on Redington is given its leading market positioning, underlying growth in the segments of operations, and ability to generate healthy OCF and superior return ratios. Risks include vendor concentration (Apple, HP, AWS, Microsoft), channel partner risk, working capital intensity in hardware, and geopolitical/FX volatility.
Investors applying robust frameworks for analyzing stock fundamentals will note that this multiple reflects the company's shift toward higher-margin software revenue.
Company website: https://redingtongroup.com/
| Rating | BUY |
|---|---|
| CMP | INR 250 |
| Target Price | INR 370 |
| Upside | 48% |
Click to download the full Redington Group IC Report
Analyst:
- Vinay Menon - Research Analyst, Institutional Equities (NISM-201600112117)
- Miloni Mehta - Research Associate, Institutional Equities (NISM-201800127664)
Access comprehensive market insights and sector-wide analysis in our Research Centre.
Related Reading Context
- "Understanding the hardware manufacturing side of India's AI boom complements the distribution narrative."
Netweb Technologies: India's AI Infrastructure Play - "For insights on how technology trends are shaping investment opportunities, check out this related resource."
Explore IT sector insights here - "Explore how other tech players are leveraging digital transformation and banking tech."
Aurionpro Solutions: The Software & Cloud Thesis
Disclaimer: - You are advised to read our disclaimer here: https://www.mnclgroup.com/disclaimers
Related Research

Ramkrishna Forgings Ltd. - Forging diversified growth levers | Initiating Coverage

TAJGVK Hotels & Resorts Ltd. - Well placed for a luxury-led growth cycle | Initiating Coverage

Carborundum Universal (CUMI) - Initiating Coverage Report

Grindwell Norton (GNO) - Initiating coverage Report


Indigo Paints - Industry-Leading Growth with Improving Margin Outlook | Initiating Coverage Report

Jubilant FoodWorks - Diversifying Growth Beyond Domino’s with Popeyes Scale-Up | Initiating Coverage Report

Bata India - Improving Consumer Sentiment; Margins to Improve Gradually | Initiating Coverage Report

Page Industries - Volume Recovery and Margins Stabilization Expected in Q2 | Initiating Coverage Report

Godrej Consumer Products - Initiating Coverage Report

Titan Company - Robust Growth; Improving Mix to Drive Margins | Initiating Coverage Report

Britannia - Demand Improvement Drives Healthy Volume Growth | Initiating Coverage Report

Bikaji Foods - Healthy Growth Despite a Challenging Environment | Initiating Coverage Report

Berger Paints - Healthy Growth Persist | Initiating Coverage Report


Metro Brands - Double-Digit Growth Sustained; Margin Profile Impacted | Initiating Coverage Report

Marico - Volume Momentum Accelerates; Margin Outlook Remains Resilient | Initiating Coverage

Kansai Nerolac - Strong Revenue Growth; Margin Recovery Expected | Initiating Coverage

Westlife Foodworld - Demand Recovery Drives SSSG; Input Cost Weigh on Margins | Initiating Coverage

Dabur India - Resilient Performance in Challenging Environment | Initiating Coverage

Asian Paints - Volume growth accelerates; Margin Guidance Maintained | Initiating Coverage

Colgate Palmolive - Premiumization Led Growth Continues; Initiate with Accumulate | Initiating Coverage

Hindustan Unilever - Volume-Led Recovery Continues; Cost Inflation Remains a Key Watchpoint | Initiating Coverage

Nestlé India Q1FY27 Review: Strong Growth & Accumulate Rating

Minda Corp. Ltd. - The Electronics Layer Beneath India’s Auto Cycle - Initiating Coverage

Travel Food Services Ltd l Gateway to India’s Aviation-Led Consumption Story - Initiating coverage

Ivalue Infoslutions Ltd - Architecting India's cybersecurity stack - Initiating coverage

Aditya Vision - Capturing the Next Wave of Bharat Consumption | Initiating Coverage Report

Sri Lotus Developers and Realty Ltd - Premium Redevelopment Compounder | Initiating Coverage Report
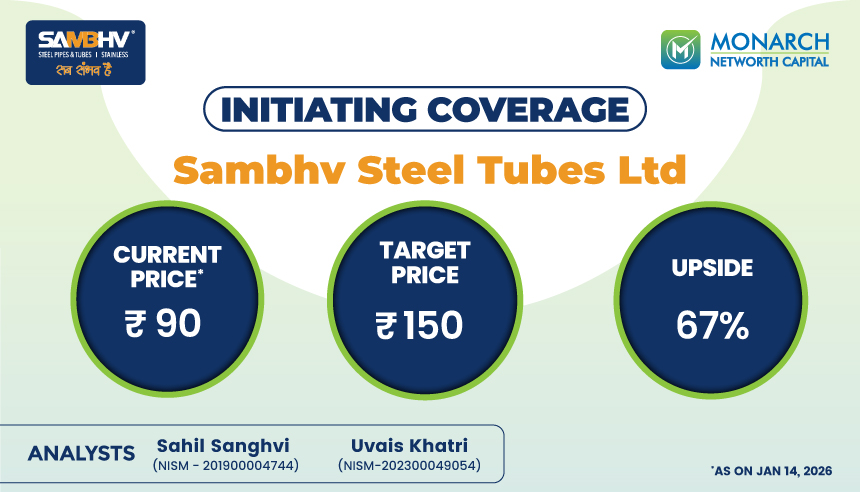
Sambhv Steel Tubes Ltd. - Mid-Metamorphosis and Mispriced - Initiating Coverage
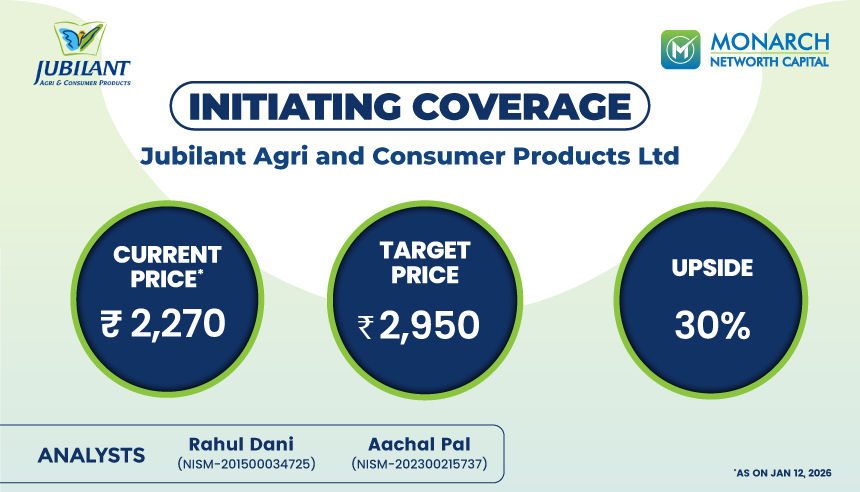
Jubilant Agri & Consumer Products - Emerging Adhesives Challenger - Initiating Coverage
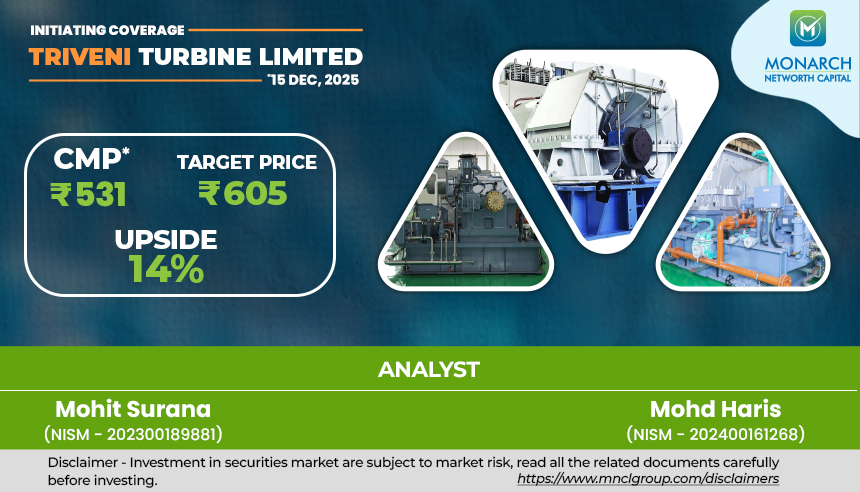
Triveni Turbine Limited (TTL) - Driving the decentralized energy wave | Initiating Coverage Report
Scoda Tubes Ltd - Integrated, Accredited and tailwind driven | Initiating Coverage Report
Redington Ltd - Where technology meets scale | Initiating Coverage Report

TD Power Systems - Plugged in to the energy transition and AI boom - Initiating Coverage Report

What is an IPO? A Beginner’s Guide to Initial Public Offerings

Inox India Ltd - Cold Precision, Hot Opportunity | Initiating Coverage Report

Netweb Technologies Ltd - Beacon of India's AI dream | Initiating Coverage Report

ASK Automotive Ltd - No brakes on growth - Initiating Coverage Report


Goldiam International Ltd - Initiating Coverage Report

Mayur Uniquoters Ltd — Initiating Coverage Report