Netweb Technologies Ltd - Beacon of India's AI dream | Initiating Coverage Report

We initiate coverage on Netweb Technologies with a BUY rating and target price of Rs 2,450. This under-researched stock is India’s only end-to-end IT solutions provider for high end computing with design and manufacturing capabilities.
Strong partnerships with chipmakers like Nvidia, Intel, and AMD help compete with global players like HP & Dell. Led by demand for HPCs, data center expansion, and initiatives like India AI mission offers a staggering 40%+ growth opportunity over the next 3-5 years. With marquee clients (ISRO, Infosys, Zoho), a Rs40bn pipeline (60% conversion rate), and expected RFP wins in H2FY26 from India AI mission (remains optionality), Netweb is well-placed for solid growth. Valuations, drawing references to fast-growing sectors / stock, offer comfort.
HPC and Private cloud primed for growth:
HPC remains at a nascent stage in India, with strong growth potential across sectors like auto (simulation), pharma (drug discovery), and FMCG (product R&D). Demand is already visible in research, defense, space, and AI development. Private cloud and HCI are poised to grow at 30%+, and Netweb offers end-to-end solutions (servers, switches, software stack), setting it apart. With current utilization at 60–65% and a new plant expected in FY26-FY27 adding 30%+ more capacity, the company has ample runway for growth.
AI – the next leg of growth:
AI systems—powered by Netweb’s hardware & software and Nvidia GPUs—are seeing rapid adoption for AI/ML tasks. With 50%+ growth, this segment could contribute ~20% of revenues by end-FY28 (14% currently). The Rs100bn India AI Mission (2025–2030) is expected to drive demand for AI R&D, where Netweb is well-positioned to compete for upcoming RFPs. Additionally, the push for AI sovereignty and homegrown LLMs may further boost demand for GPUs and AI infrastructure.
Market leader in India with end-to-end integration:
Netweb stands apart from traditional box sellers by fully designing 24-layer PCBs for manufacturing high end servers, and in-house developed software stack. With no direct Indian competitors, it competes with global giants like Dell, HP, Nutanix and VMware. Its ability to offer vertical focused, cost-optimized hardware-software bundles enhances client ROI and strengthens deal wins. Operating across high-growth TAMs with natural cross-sell potential, and high entry barriers, Netweb is well-positioned for sustained advantage.
Valuations, view & risks:
Diversified revenue across multiple tech verticals, a large addressable market, consistent deal wins, and a strong pipeline provide strong visibility and comfort. We model in 43.5%/45.6%/48.6% Revenue/EBITDA/PAT CAGR over FY25–FY27E. Initiate with a BUY and TP at Rs2,450 (valued at 55x FY27E PE). Our base case does not include potential upside from India’s AI mission. Bear-case/Bull-case TP stands at Rs 1,505 / Rs 2,770. We draw parallels from EMS players on growth / valuations. Our positive stance on the co. is further substantiated by our interaction with laterals - including peers and clients that point to favorable sector dynamics and growth drivers. Key risks: Reduced government spends on HPCs, slower enterprise adoption of private cloud and AI Systems and geopolitical disruptions in Taiwan affecting component supply.
Rating: BUY
CMP: Rs 1,842
Target Price: Rs 2,450
Upside: 33% 
Click to download the full Netweb Technologies Ltd. IC Report
Analyst: Analysts Vinay Menon (NISM - 201600112117) & Miloni Mehta (NISM – 201800127664)
Company website: https://netwebindia.com/
Disclaimer: You are advised to read our disclaimer here: Click to view
Related Research

Ramkrishna Forgings Ltd. - Forging diversified growth levers | Initiating Coverage

TAJGVK Hotels & Resorts Ltd. - Well placed for a luxury-led growth cycle | Initiating Coverage

Carborundum Universal (CUMI) - Initiating Coverage Report

Grindwell Norton (GNO) - Initiating coverage Report


Indigo Paints - Industry-Leading Growth with Improving Margin Outlook | Initiating Coverage Report

Jubilant FoodWorks - Diversifying Growth Beyond Domino’s with Popeyes Scale-Up | Initiating Coverage Report

Bata India - Improving Consumer Sentiment; Margins to Improve Gradually | Initiating Coverage Report

Page Industries - Volume Recovery and Margins Stabilization Expected in Q2 | Initiating Coverage Report

Godrej Consumer Products - Initiating Coverage Report

Titan Company - Robust Growth; Improving Mix to Drive Margins | Initiating Coverage Report

Britannia - Demand Improvement Drives Healthy Volume Growth | Initiating Coverage Report

Bikaji Foods - Healthy Growth Despite a Challenging Environment | Initiating Coverage Report

Berger Paints - Healthy Growth Persist | Initiating Coverage Report


Metro Brands - Double-Digit Growth Sustained; Margin Profile Impacted | Initiating Coverage Report

Marico - Volume Momentum Accelerates; Margin Outlook Remains Resilient | Initiating Coverage

Kansai Nerolac - Strong Revenue Growth; Margin Recovery Expected | Initiating Coverage

Westlife Foodworld - Demand Recovery Drives SSSG; Input Cost Weigh on Margins | Initiating Coverage

Dabur India - Resilient Performance in Challenging Environment | Initiating Coverage

Asian Paints - Volume growth accelerates; Margin Guidance Maintained | Initiating Coverage

Colgate Palmolive - Premiumization Led Growth Continues; Initiate with Accumulate | Initiating Coverage

Hindustan Unilever - Volume-Led Recovery Continues; Cost Inflation Remains a Key Watchpoint | Initiating Coverage

Nestlé India Q1FY27 Review: Strong Growth & Accumulate Rating

Minda Corp. Ltd. - The Electronics Layer Beneath India’s Auto Cycle - Initiating Coverage

Travel Food Services Ltd l Gateway to India’s Aviation-Led Consumption Story - Initiating coverage

Ivalue Infoslutions Ltd - Architecting India's cybersecurity stack - Initiating coverage

Aditya Vision - Capturing the Next Wave of Bharat Consumption | Initiating Coverage Report

Sri Lotus Developers and Realty Ltd - Premium Redevelopment Compounder | Initiating Coverage Report
Sambhv Steel Tubes Ltd. - Mid-Metamorphosis and Mispriced - Initiating Coverage
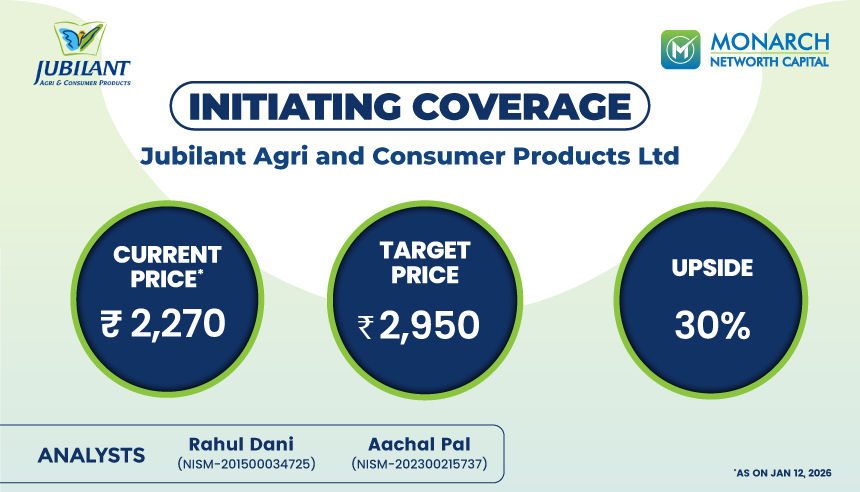
Jubilant Agri & Consumer Products - Emerging Adhesives Challenger - Initiating Coverage
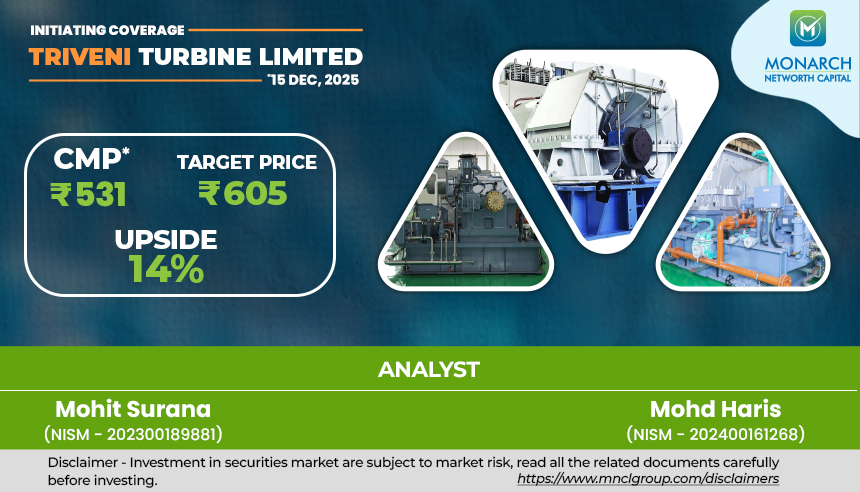
Triveni Turbine Limited (TTL) - Driving the decentralized energy wave | Initiating Coverage Report
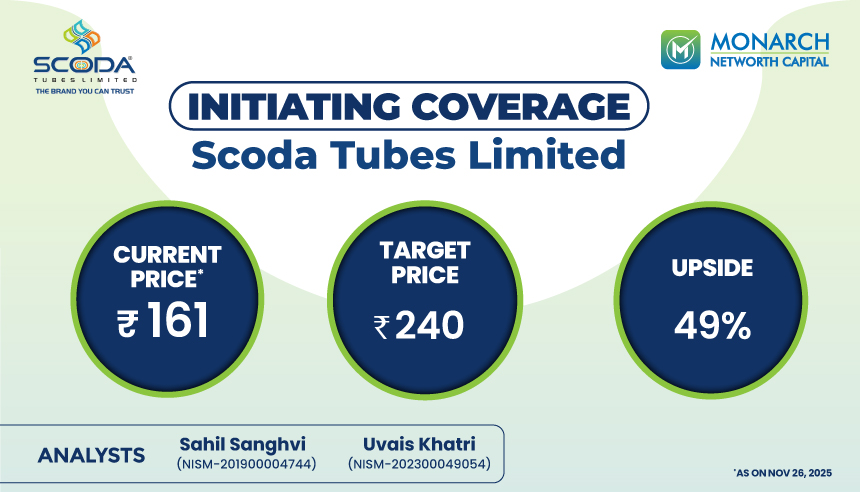
Scoda Tubes Ltd - Integrated, Accredited and tailwind driven | Initiating Coverage Report
Redington Ltd - Where technology meets scale | Initiating Coverage Report

TD Power Systems - Plugged in to the energy transition and AI boom - Initiating Coverage Report

What is an IPO? A Beginner’s Guide to Initial Public Offerings

Inox India Ltd - Cold Precision, Hot Opportunity | Initiating Coverage Report
Netweb Technologies Ltd - Beacon of India's AI dream | Initiating Coverage Report

ASK Automotive Ltd - No brakes on growth - Initiating Coverage Report


Goldiam International Ltd - Initiating Coverage Report

Mayur Uniquoters Ltd — Initiating Coverage Report