Colgate Palmolive - Premiumization Led Growth Continues; Initiate with Accumulate | Initiating Coverage

Colgate reported healthy double-digit revenue growth of 11.8% YoY, the strongest in the last seven quarters, primarily driven by high-single-digit volume growth in the toothpaste portfolio. Growth was led by the strong performance of the premium toothpaste segment, sustained momentum in the core portfolio and broad-based growth across the company's overall product portfolio. The company posted strong volume growth in the oral care segment, outperforming HUL's mid-single digit growth and remaining broadly in line with Dabur's near double-digit growth. GM expanded by 100bps YoY to 70.0%, enabling higher investments in brand building and premiumization. The company has maintained average GM of 70.0% over the past 13 quarters. However, EBITDAM contracted by 140bps YoY to 30.1% due to 260bps increase in ad spends. The company has historically maintained advertising spends in the range of 13–15% of sales, and the management expects this investment level to increase going forward. The company expects to mitigate commodity cost volatility through cost-saving initiatives and calibrated pricing actions, while maintaining a healthy margin profile despite geopolitical uncertainties. The company has reported two consecutives of strong numbers, and we expect this momentum to continue going ahead in terms of topline. EBITDAM is expected to remain under pressure, as the company would continue to invest behind the brands while increasing competition and better product offerings by competitors remain a challenge. Accordingly, we initiate coverage on Colgate Palmolive (India) with an 'Accumulate' rating. Valuing the stock at 40x FY28E EPS, we arrive at a target price of Rs. 2,380.
Q1FY27 Performance:
Result in line with consensus estimates: Net revenue grew by 11.8% YoY to Rs 16.0bn led by broad based growth across the entire portfolio. GM expanded by 100bps YoY to 70.0%. A 100/20bps decline in RM cost/employee expenses was fully offset by 260/10bps increase in ad spends/other expenses. Consequently, EBITDA margin contracted by 140bps YoY to 30.1%. EBITDA grew by 6.7% YoY to Rs 4.8bn. APAT grew by 8.0% YoY to Rs 3.5bn.
Premiumization Drives Growth:
Colgate delivered a strong 11.8% YoY revenue growth, driven by high-single digit toothpaste volume growth, premiumisation, and broad-based portfolio strength. Management remains confident of sustaining healthy margins through cost efficiencies, disciplined cost management and continued investments in innovation and brand building. Innovation remained a key growth driver, with the company strengthening its premium portfolio through the launch of ‘Colgate MaxFresh Berry Blast’ and the ‘Colgate Total Active Prevention Foaming Clean Toothbrush’. The company also intensified marketing efforts with a summer campaign for ‘Colgate MaxFresh Peppermint Ice’, aimed at driving premiumisation and enhancing consumer engagement.
Outlook:
We expect Colgate-Palmolive India to deliver healthy growth, driven by premiumization, innovation, distribution expansion and strong brand investments. However, sustaining high volume growth and gaining market share would remain a challenge given increased competition. While higher advertising spending and input cost inflation may keep margins range-bound in the near term, operational efficiencies and calibrated pricing should support sustainable profitable growth.
Valuation:
We forecast Revenue/EBITDA/PAT CAGR of 8.3/9.1/9.4% over FY26 FY28E. We expect Colgate-Palmolive India to sustain healthy growth, supported by premiumization, innovation and MS gains. While near-term margins may remain under pressure due to higher brand investments and increased competition, we believe earnings growth will remain healthy. Accordingly, we initiate coverage with an 'Accumulate' rating and a TP of Rs. 2,380, based on 40x FY28E EPS.
Company website: https://www.colgatepalmolive.co.in/
| Rating | Accumulate |
|---|---|
| CMP* | INR 2,166 |
| Target Price | INR 2,380 |
| Upside | 10% |
*CMP is as per report published date
Click to download the full Colgate Palmolive India Ltd Q1FY27 Company Update
Analyst:
- Sachin Bobade - HOR, Institutional Equities (NISM-201700098683)
- Akshay Patel - Senior Research Associate, Institutional Equities (NISM-202100071038)
Frequently Asked Questions (FAQs) – Colgate Palmolive India's Q1FY27 Company Update
1. What drove Colgate Palmolive India's Q1FY27 growth?
Growth was supported by high-single-digit toothpaste volume growth, premiumization, strong consumer demand and broad-based performance across the company's oral care portfolio.
2. Why did operating margins decline despite higher revenue?
Operating margins moderated due to increased advertising and brand-building investments, even as gross margins remained strong through disciplined cost management and operational efficiencies.
3. What are Colgate Palmolive India's long-term growth drivers?
Premiumization, product innovation, wider distribution, brand investments, market expansion and growing consumer preference for premium oral care products remain key long-term growth drivers.
4. What risks should investors monitor?
Higher commodity costs, increased competition, sustained advertising expenses, changing consumer preferences and broader economic conditions could affect future profitability and growth.
5. Why does the institutional research report have an Accumulate rating?
The research view reflects confidence in Colgate's premiumization strategy, innovation pipeline, strong brand leadership and steady earnings outlook, while recognizing near-term margin pressure from elevated brand investments.
Before You Trade, Strengthen Your Foundations with These Guides
- For a stronger understanding of indicators such as RSI, VWAP, and trendlines, check our 👉 Technical Analysis Fundamentals section.
- Want to refine your risk-reward planning? Explore our insights on 👉 Position Sizing & Risk Management Strategies.
- Click here for Colgate Palmolive India Ltd. research reports, stock price chart and more
Disclaimer: - Investments in securities market are subject to market risk, read all the related document carefully before investing. https://www.mnclgroup.com/research-disclaimer
Related Research

Ramkrishna Forgings Ltd. - Forging diversified growth levers | Initiating Coverage

TAJGVK Hotels & Resorts Ltd. - Well placed for a luxury-led growth cycle | Initiating Coverage

Carborundum Universal (CUMI) - Initiating Coverage Report

Grindwell Norton (GNO) - Initiating coverage Report


Indigo Paints - Industry-Leading Growth with Improving Margin Outlook | Initiating Coverage Report

Jubilant FoodWorks - Diversifying Growth Beyond Domino’s with Popeyes Scale-Up | Initiating Coverage Report

Bata India - Improving Consumer Sentiment; Margins to Improve Gradually | Initiating Coverage Report

Page Industries - Volume Recovery and Margins Stabilization Expected in Q2 | Initiating Coverage Report

Godrej Consumer Products - Initiating Coverage Report

Titan Company - Robust Growth; Improving Mix to Drive Margins | Initiating Coverage Report

Britannia - Demand Improvement Drives Healthy Volume Growth | Initiating Coverage Report

Bikaji Foods - Healthy Growth Despite a Challenging Environment | Initiating Coverage Report

Berger Paints - Healthy Growth Persist | Initiating Coverage Report


Metro Brands - Double-Digit Growth Sustained; Margin Profile Impacted | Initiating Coverage Report

Marico - Volume Momentum Accelerates; Margin Outlook Remains Resilient | Initiating Coverage

Kansai Nerolac - Strong Revenue Growth; Margin Recovery Expected | Initiating Coverage

Westlife Foodworld - Demand Recovery Drives SSSG; Input Cost Weigh on Margins | Initiating Coverage

Dabur India - Resilient Performance in Challenging Environment | Initiating Coverage

Asian Paints - Volume growth accelerates; Margin Guidance Maintained | Initiating Coverage
Colgate Palmolive - Premiumization Led Growth Continues; Initiate with Accumulate | Initiating Coverage

Hindustan Unilever - Volume-Led Recovery Continues; Cost Inflation Remains a Key Watchpoint | Initiating Coverage

Nestlé India Q1FY27 Review: Strong Growth & Accumulate Rating

Minda Corp. Ltd. - The Electronics Layer Beneath India’s Auto Cycle - Initiating Coverage

Travel Food Services Ltd l Gateway to India’s Aviation-Led Consumption Story - Initiating coverage

Ivalue Infoslutions Ltd - Architecting India's cybersecurity stack - Initiating coverage

Aditya Vision - Capturing the Next Wave of Bharat Consumption | Initiating Coverage Report

Sri Lotus Developers and Realty Ltd - Premium Redevelopment Compounder | Initiating Coverage Report
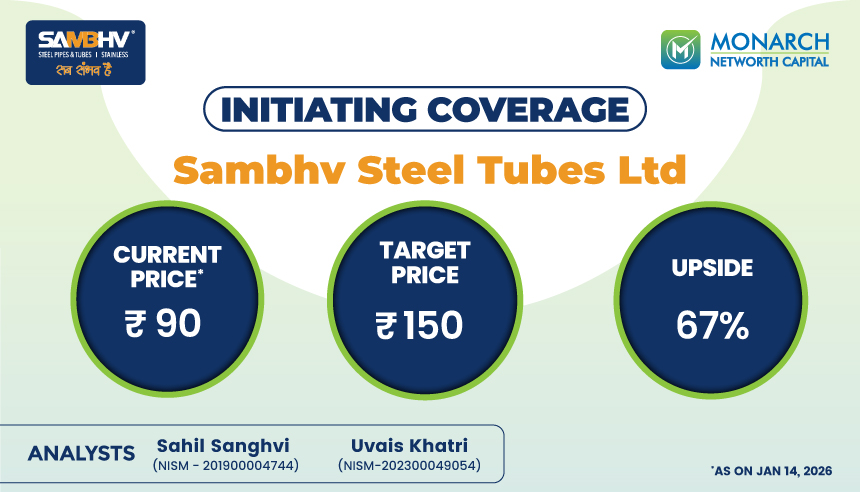
Sambhv Steel Tubes Ltd. - Mid-Metamorphosis and Mispriced - Initiating Coverage
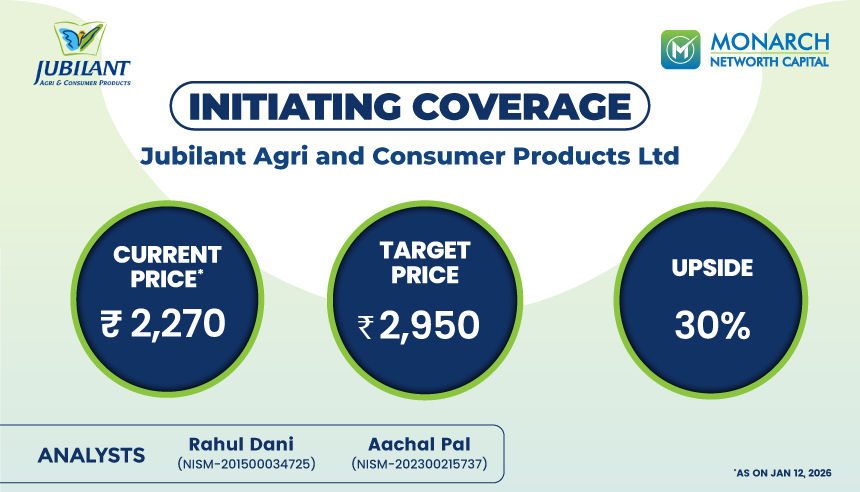
Jubilant Agri & Consumer Products - Emerging Adhesives Challenger - Initiating Coverage
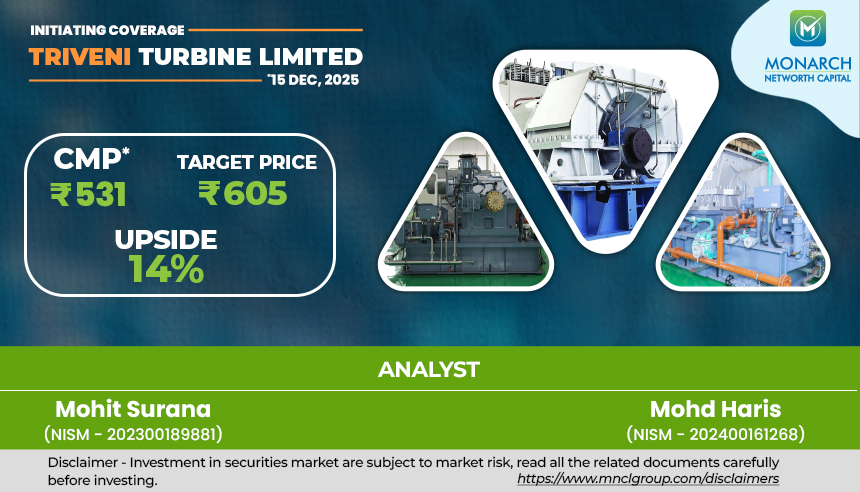
Triveni Turbine Limited (TTL) - Driving the decentralized energy wave | Initiating Coverage Report
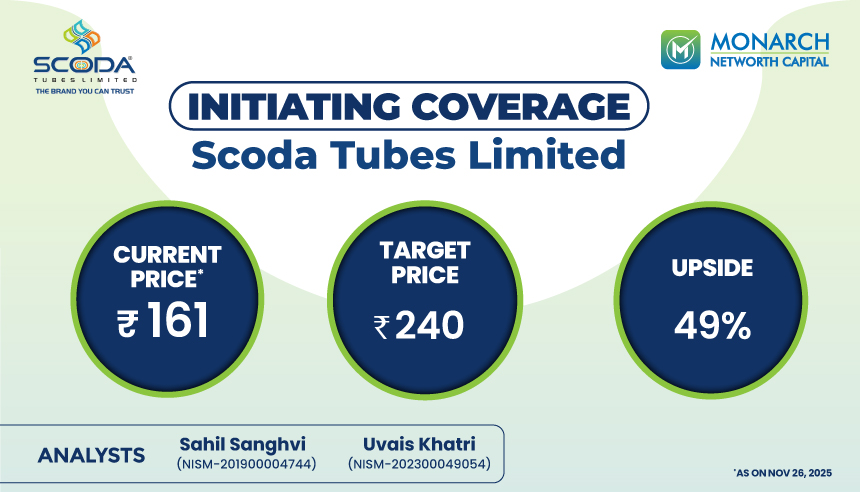
Scoda Tubes Ltd - Integrated, Accredited and tailwind driven | Initiating Coverage Report
Redington Ltd - Where technology meets scale | Initiating Coverage Report

TD Power Systems - Plugged in to the energy transition and AI boom - Initiating Coverage Report

What is an IPO? A Beginner’s Guide to Initial Public Offerings

Inox India Ltd - Cold Precision, Hot Opportunity | Initiating Coverage Report

Netweb Technologies Ltd - Beacon of India's AI dream | Initiating Coverage Report

ASK Automotive Ltd - No brakes on growth - Initiating Coverage Report


Goldiam International Ltd - Initiating Coverage Report

Mayur Uniquoters Ltd — Initiating Coverage Report